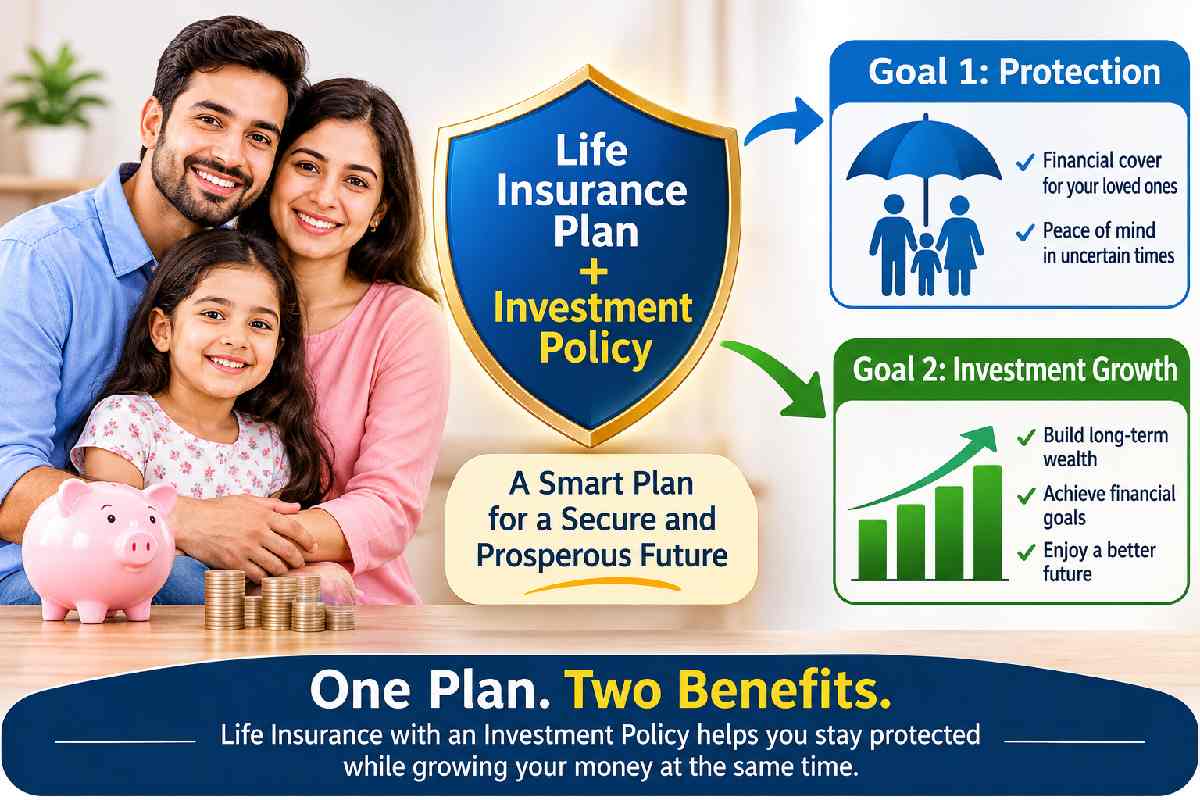
Many people want financial protection for their families and also want to build funds for future goals. Managing both through separate products is one option. Another is a life insurance plan that includes an investment or savings component, designed to address protection and wealth creation within a single policy. The structure, benefits and risks depend on the type of plan and its terms and conditions. This article explains how an investment policy inside a life insurance plan can serve two goals at once.
Table of Contents
What Is an Investment Policy Inside a Life Insurance Plan?
In an investment-oriented or savings-oriented life insurance plan, life coverage is combined with the aspect of savings or investments. In this kind of a life insurance plan, part of the premium is paid to get the benefit of life insurance, while the rest of the amount goes to the investment or savings component of the plan.
There are differences in the workings of both components in different kinds of life insurance plans. Some plans include the investment part as a market-oriented plan, while some have the conventional savings feature. These details will be mentioned in the policy.
How Can One Plan Address Two Goals?
The two goals handled by such a plan are different in nature but can be planned together.
Goal 1: Financial Protection
The life cover component provides a death benefit to nominees if the policyholder passes away during the policy term, subject to the policy conditions. This helps address the financial responsibilities of dependants.
Goal 2: Long-Term Wealth Creation
The savings or investment component can help in creating a fund, which can be useful in meeting any goal like education, making any purchases or supplementing the retirement savings fund.
Understanding the Two Components
| Component | Purpose | Key Point to Understand |
| Life cover | Financial protection for nominees | The death benefit is payable subject to policy terms and conditions |
| Investment or savings | Building a fund for future goals | Benefits depend on the plan structure, and market-linked options carry investment risk |
Why Some People Prefer a Combined Approach
A combined investment policy may suit an individual for various reasons:
- Ease: It may be simpler to manage one policy than multiple different products.
- Consistency: The discipline of making payments regularly may result in consistent savings over time.
- Time period: The period of the policy can be matched to the time duration of a financial objective.
How a Combined Plan Differs From Pure Protection
| Factor | Pure Protection Plan | Plan With an Investment Component |
| Primary focus | Life cover for a defined period | Life cover along with a savings or investment element |
| Premium structure | Generally focused on the cost of cover | Part of the premium may go towards the investment component |
| Benefits | Death benefit, subject to terms | Death benefit and, depending on the product, maturity or other benefits |
| Risk factors | Policy conditions and exclusions | Policy conditions, charges and, in market-linked plans, investment risk |
Factors That Can Influence How Well a Plan Serves Both Goals
The way a plan performs against both goals depends on several elements. The policy term affects how long premiums are paid and how long the fund can grow. The premium amount influences both the level of cover and the amount directed towards the investment component. Charges, which can include premium allocation, fund management and policy administration charges, affect the value of the investment component. In market-linked plans, fund choice and market conditions also play a role.
What to Consider Before Choosing
A few questions can help in evaluating such a plan:
| Factor | What to Consider |
| Protection need | Is the life cover adequate for your family’s financial responsibilities? |
| Financial goal | What are you saving for, and how far away is the goal? |
| Risk comfort | Are you comfortable with the investment risk, if the plan is market-linked? |
| Policy term | Does the term match the timeline of your goal? |
| Charges | What charges apply, and how may they affect the fund value? |
| Lock-in and liquidity | Are there lock-in periods or conditions on withdrawals and surrender? |
| Premium commitment | Can you continue paying premiums throughout the policy term? |
| Future reviews | Could changes in income or goals require a review of the plan? |
Conclusion
An investment policy inside a life insurance plan can help address financial protection and long-term savings together, with the life cover supporting nominees and the investment component supporting future goals. Because the structure, charges and risks differ across products, understanding how each component works is important before choosing. Reputed platforms like Tata AIA offer life insurance plans with savings and investment features that may be considered by individuals seeking this combination, subject to applicable policy terms, underwriting requirements and regulatory guidelines. Reviewing the plan periodically can help ensure it continues to match changes in income, responsibilities and financial objectives.